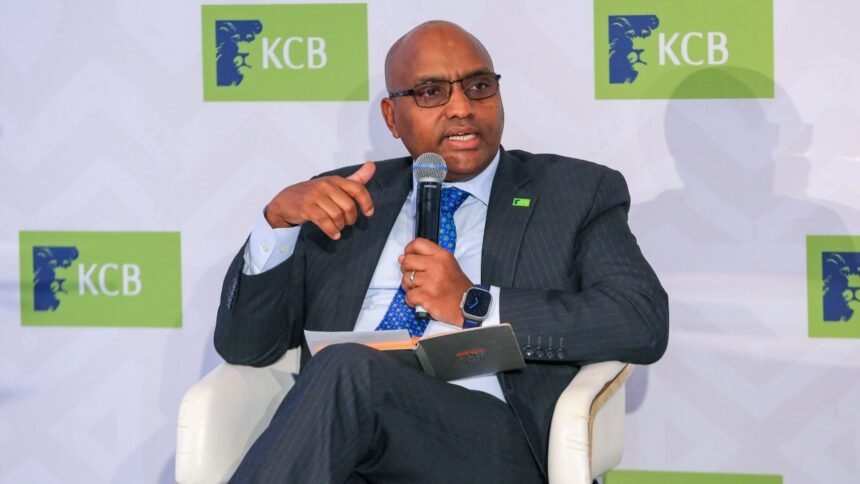
Kenya’s banks are opening their lending taps further to small businesses, extending KSh424.67 billion in new loans to micro, small and medium enterprises (MSMEs) between January and September 2026.
The amount is equivalent to a 30% increase from the KSh326.5 billion advanced during the same period in 2025, putting lenders within reach of their KSh500 billion annual MSME lending target.
If the momentum holds through December, 2026 could become the strongest year yet for bank financing to Kenya’s small-business sector.
The improvement comes as borrowing costs gradually ease, offering businesses some relief after a prolonged period of expensive credit that constrained investment, working capital, and expansion.
“While the growth in lending shows that banks are increasing their support for small businesses, the next priority is to reach more businesses, including businesses borrowing from banks for the first time and those that have previously struggled to access credit,” said Kenya Bankers Association (KBA).
Average commercial bank lending rates fell to 14.4% in September 2026, down from 17.2% in November 2024.
There are also signs that credit conditions across the wider economy are improving. Private-sector lending growth reached 10.6% in September, compared with 10.3% in August, pointing to a gradual recovery in banks’ willingness to extend credit to businesses and other borrowers.
Banks see improvement in loan repayments
Kenyan banks are also recording improvements in loan repayment performance, beyond the increase in lending.
The gross non-performing loans (NPL) ratio declined to 13.9% in September 2026, from 14.8% in June and 17.6% in August 2025.
The decline suggests that a smaller proportion of outstanding bank loans is falling into repayment difficulties, an encouraging development for lenders that have had to balance supporting borrowers with protecting the quality of their loan books.
What this means is that better repayment performance creates room to extend more credit without exposing their balance sheets to excessive risk. For businesses, it could gradually improve confidence in the lending environment.
However, the growth in loan disbursements does not necessarily mean that credit has become accessible to every business.
The real test is who gets the money
Kenya’s MSME sector remains one of the most important sources of employment and economic activity, but many small businesses continue to face difficulties securing formal financing.
Businesses without sufficient collateral, established credit histories or predictable cash flows can still struggle to meet traditional bank lending requirements.
This means the next phase of banking sector growth will need to go beyond increasing the amount of money disbursed. Banks will have to reach businesses borrowing formally for the first time, including those previously considered too risky or difficult to assess.
There is also a growing need for longer-term financing. While short-term loans can help businesses manage daily operations, access to longer repayment facilities is critical for purchasing machinery, investing in technology, opening new branches and expanding production capacity.
The KSh500 billion target will be an important milestone, but the bigger measure of success will be how many businesses secure financing, grow their operations, employ more people and build sustainable enterprises