- NIGERIA | DANGOTE REFINERY IPO CLOSES TUESDAY
- EGYPT | BANQUE DU CAIRE SETS ITS PRICE
- KENYA | QUICKMART OFFER CLOSES FRIDAY
- SENEGAL | SONATEL SPLIT TAKES EFFECT
- MOROCCO | 2027 BUDGET STARTS ITS 30-DAY CLOCK
- BOTSWANA | BANK OF BOTSWANA DECIDES THURSDAY
- ETHIOPIA | EUROBOND SWAP SET FOR DECEMBER
- GHANA | 2027 BUDGET DUE IN EARLY NOVEMBER
- AFRICA | FED DECIDES AS $46 BILLION OF EUROBONDS COME DUE
- WHAT TO EXPECT
NIGERIA | DANGOTE REFINERY IPO CLOSES TUESDAY
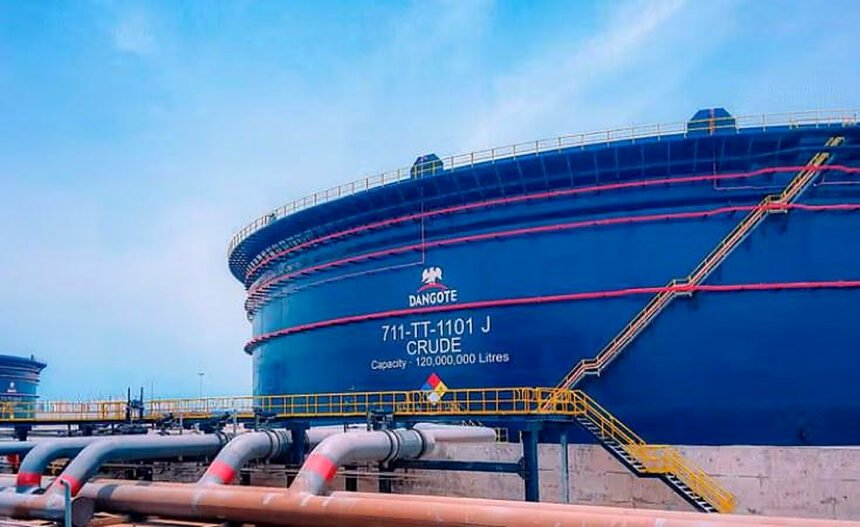
Nigeria’s Dangote Petroleum Refinery and Petrochemicals closes applications for its initial public offering on Tuesday, 27 October, two weeks later than first planned after the Securities and Exchange Commission approved an extension. The company is offering 4.1 billion shares at ₦525 (about $0.40) each, which would raise roughly ₦2.15 trillion (about $1.6 billion) if fully taken up, with proceeds going towards plans to double the Lekki refinery’s capacity to 1.4 million barrels a day.
Aliko Dangote told reporters during a refinery tour that orders had already reached three to four times the amount the company set out to sell. Temi Popoola, chief executive of Nigerian Exchange Group, said on 22 October that the offer could increase the number of active investors in Nigeria’s market as much as fivefold, with subscriptions taken through WhatsApp, point-of-sale terminals and basic mobile phones.
The revised timetable puts application returns by 3 November, the proposed allocation with the SEC on 10 November and regulatory clearance by 17 November, with trading on the Nigerian Exchange set for early December. Kenya and Uganda have allowed their citizens to take part, while Ethiopia’s Capital Market Authority has limited the offer there to qualified investors. Allotment is the process of deciding how many shares each applicant actually receives when demand exceeds the shares available.
EGYPT | BANQUE DU CAIRE SETS ITS PRICE
Egypt’s Banque du Caire is due to announce the final price for its initial public offering on Monday, 26 October, with the retail book open until Wednesday, 28 October. Its state-owned parent, Banque Misr, has enlarged the sale to 45% of the bank from 30%, and the European Bank for Reconstruction and Development and the International Finance Corporation have each agreed to take up to 15.74% of the first private placement tranche.
The indicative range is EGP 4.82 to EGP 5.30 (about $0.09 to $0.10) a share. The top of the range values the bank at about EGP 80.8 billion (about $1.5 billion), and a 45% sale at that price would raise about EGP 36.4 billion (about $680 million). The sale involves only existing shares, so the proceeds go to Banque Misr rather than to the bank.
Retail orders reached 581.4 million shares on Sunday, 25 October, or 2.54 times the 228.75 million shares originally set aside for the public, on a day all three main EGX indices closed sharply lower. Trading under the ticker BQDC is expected to begin on or about 2 November. The offer circular includes a 30-day stabilisation mechanism, under which retail buyers can sell shares back at the offer price if the stock trades below it.
The listing follows Moody’s upgrade of Egypt’s sovereign rating to B3 from Caa1 on 16 October, which cited a primary budget surplus of 4.9% of GDP in the year to June 2026 and reserves of $57 billion in September.
KENYA | QUICKMART OFFER CLOSES FRIDAY
Kenya’s Quickmart, the country’s second-largest supermarket chain, closes its initial public offering at 5pm on Friday, 30 October. Sokoni Retail Kenya, the holding vehicle of the founders and private equity firm Adenia Partners, is selling 2 billion existing shares, half the company, at KSh7.50 (about $0.06) each, seeking KSh15 billion (about $116 million) and valuing the retailer at KSh30 billion (about $232 million).
The offer is not underwritten and lapses unless investors take up at least 75% of the shares, or 1.5 billion, by the closing date, in which case all money is refunded. The International Finance Corporation has committed up to $15 million, about 13% of the offer, subject to its board’s approval. An underwritten offer is one where banks guarantee to buy any unsold shares; Quickmart’s is not, which is why the 75% threshold decides whether the listing goes ahead.
Shares are due in investors’ Central Depository System accounts on 11 November, with trading on the Nairobi Securities Exchange expected on 12 November. Quickmart would be the bourse’s second IPO of 2026, after the government’s sale of a 65% stake in Kenya Pipeline Company in March. Kenya Pipeline reported its first results as a listed company this month, with profit after tax up 13.1% to KSh11.58 billion (about $90 million) for FY2026, about 21% above the forecast in its IPO prospectus.
SOUTH AFRICA | FUEL LEVY CUT STARTS 4 NOVEMBER
South Africa’s motorists get a temporary cut to the general fuel levy from 4 November, announced by Finance Minister Enoch Godongwana in the Medium-Term Budget Policy Statement on 21 October. The levy falls by R1.50 (about $0.09) a litre on petrol and R3 (about $0.18) on diesel until 1 December, then by R1 (about $0.06) and R1.50 (about $0.09) a litre until 5 January.
The relief is funded by R10 billion (about $607 million) that the Central Energy Fund will return to the National Revenue Fund. Treasury director-general Duncan Pieterse said fuel revenue would be about R30 billion (about $1.8 billion) lower than expected in 2026/27 because of levy relief and changes in consumer behaviour.
Petrol 95 sold at about R30.25 (about $1.84) a litre inland in October. The Department of Mineral and Petroleum Resources is due to announce November pump prices ahead of 4 November, the date the levy cut takes effect. Concerned Citizens of South Africa, which called a national shutdown over fuel prices on 19 October, had demanded a 50% cut in pump prices. The general fuel levy is a fixed tax per litre built into the pump price, separate from the Road Accident Fund levy.
SENEGAL | SONATEL SPLIT TAKES EFFECT
Senegal’s Sonatel begins trading on a split basis on the BRVM, the regional exchange for eight West African countries, when the market opens on Monday, 26 October. Shareholders approved the 10-for-1 split at an extraordinary general meeting on 8 October, taking the number of shares to 1 billion from 100 million while share capital stays at CFA 50 billion (about $89 million).
Friday, 23 October, was the last session at the old nominal value. The stock closed at CFA 42,800 (about $76) on 19 October, equivalent to CFA 4,280 (about $7.60) after the split. The BRVM will publish the adjusted reference price in its official bulletin.
The company said the split is meant to make the shares more accessible and widen its shareholder base, at no cost to existing holders. Sonatel last split its shares in 2012. The BRVM Composite index fell 2.61% in the week to 16 October but remained up 54.04% for the year. A stock split divides each existing share into several cheaper ones without changing the company’s total value or any shareholder’s stake.
MOROCCO | 2027 BUDGET STARTS ITS 30-DAY CLOCK
Morocco’s House of Representatives now has the 2027 finance bill before it, the first budget of Head of Government Fatima Ezzahra El Mansouri’s coalition, which Economy and Finance Minister Fouzi Lekjaa presented to a joint sitting of both chambers on Friday, 23 October.
The bill puts total state spending at MAD 825.59 billion (about $90 billion), up 8.44% from MAD 761.30 billion (about $83 billion) in 2026, according to its presentation note, with operating spending up 11.41% to MAD 387.14 billion (about $42 billion) and tax revenue projected at MAD 437.40 billion (about $48 billion). Lekjaa told Parliament the government targets a budget deficit of 3% of GDP, public investment of MAD 400 billion (about $43 billion) and MAD 62 billion (about $6.7 billion) of social and economic support.
The organic budget law gives the House of Representatives 30 days to vote, followed by 22 days in the House of Councillors and a six-day second reading, with final adoption required before 31 December. The coalition holds 210 of the 395 seats in the lower house after the 23 September election. The Casablanca bourse’s MASI index was down 9.8% for the year as of 7 October, according to Bank Al-Maghrib. A finance bill is the annual law that authorises the state’s revenue and spending for the coming year.
BOTSWANA | BANK OF BOTSWANA DECIDES THURSDAY
Botswana’s central bank Monetary Policy Committee meets on Thursday, 29 October, with its policy rate at 5.5% after a 200-basis-point increase from 3.5% on 30 April and a hold on 27 August. Statistics Botswana reported on 15 October that annual inflation slowed to 7.8% in September from 9.3% in August, still above the bank’s medium-term objective range of 3% to 6%.
Governor Lesego Moseki said in August that the committee expected inflation to stay above that range until the first quarter of 2027 and to average 7.9% in 2026, with risks tilted upward by fuel prices and electricity tariffs. He attributed the July fall in inflation mainly to a cut in domestic fuel prices on 7 July, which took 2.3 percentage points off the headline rate.
Commercial banks’ average prime lending rate stood at 7.19% in July, according to the bank. The committee’s final meeting of the year is scheduled for 3 December. A basis point is one hundredth of a percentage point, so the April increase raised the rate by two full percentage points.
ETHIOPIA | EUROBOND SWAP SET FOR DECEMBER
Ethiopia’s central bank governor, Eyob Tekalegn, told Addis Fortune in an interview published on 17 October that the exchange of the country’s defaulted $1 billion Eurobond will be completed by December. The terms, agreed in principle with a bondholder committee on 29 June, would swap the old notes for a new $880 million bond, a 12% reduction in principal, carrying a 6.15% coupon and repaid in instalments to July 2029.
Official creditors, co-chaired by France and China, found the terms consistent with comparable treatment in August, but bondholders still have to approve the exchange formally. Fitch Ratings affirmed Ethiopia at Restricted Default on 16 October and said it would assign a new rating once the commercial debt terms are implemented.
The Global Sovereign Debt Roundtable’s progress report, released on 14 October, listed Ethiopia as the only one of six post-pandemic restructuring cases yet to close its bond exchange. Fitch estimated gross reserves at the National Bank of Ethiopia at $5.9 billion in FY26, about 2.5 months of import cover. A restricted default rating means a borrower has missed payments on some obligations but continues to pay others.
GHANA | 2027 BUDGET DUE IN EARLY NOVEMBER
Ghana’s Finance Minister Cassiel Ato Forson has said the 2027 budget will go to Parliament in the first week of November, within the 15 November deadline set by the Public Financial Management Act. He said it will set out business incentives and infrastructure plans linked to a new economic programme under which the government plans to invest about $10 billion. Ghana has ruled out a Eurobond in 2026 and is financing itself domestically.
The cedi traded at GH¢11.55 to the dollar in September, a 9.5% depreciation on the interbank market for the year to date, according to Bank of Ghana data. Inflation rose for a second month to 5.2% in September.
The Ghana Stock Exchange gained 2.92% in the week to 16 October, the strongest among African markets that week, and was up 63.83% for the year in local currency. A budget statement sets out the government’s tax and spending plans for the next financial year, which in Ghana begins on 1 January.
AFRICA | FED DECIDES AS $46 BILLION OF EUROBONDS COME DUE
Africa’s sovereign borrowers face a US Federal Reserve rate decision on Wednesday, 28 October, with about $46 billion of Eurobond principal falling due across the continent between 2027 and 2030, according to a report published on 12 October by Denmark’s Export and Investment Fund.
Five African sovereigns had dollar bond yields above 10% on 7 October, led by Senegal at 20.8%, and Egypt accounts for about 30% of the principal due over the period. Eight African sovereign Eurobonds have been issued at yields above 10% since 2024, against two between 2006 and 2023, the report found.
The US 10-year Treasury yield rose to 5.3% in October, its highest in 24 years, amid oil-driven inflation and expectations of Fed rate increases, Ecofin Agency reported. The IMF puts sub-Saharan African Eurobond issuance at $14 billion in 2025 and $5.5 billion in the first two months of 2026. Kenya’s Treasury has pencilled in an $815 million Eurobond for October to December. A Eurobond is a bond a government sells to international investors in a foreign currency, usually dollars, which is why US interest rates feed directly into what African issuers pay.
WHAT TO EXPECT
Monday, 26 October: Sonatel trades split-adjusted on the BRVM. Banque du Caire is due to announce its final IPO price.
Tuesday, 27 October: Dangote Petroleum Refinery’s IPO closes.
Wednesday, 28 October: Banque du Caire’s retail tranche closes. The US Federal Reserve announces its rate decision.
Thursday, 29 October: Bank of Botswana Monetary Policy Committee. The European Central Bank and Bank of Japan also decide this week.
Friday, 30 October: Quickmart’s IPO closes at 5pm Nairobi time.
Further out: Banque du Caire trading is expected around 2 November, South Africa’s fuel levy cut begins on 4 November and Ghana’s 2027 budget is expected in the first week of November. Quickmart lists on 12 November, Dangote’s allotment clearance is due by 17 November, the Central Bank of Nigeria’s MPC meets on 23 and 24 November, and Kenya’s High Court resumes the Dangote Lamu refinery case on 24 November.
Sable Daily brings together the developments shaping Africa’s businesses, markets, and economies, so you can stay informed and make sense of what is happening across the continent.