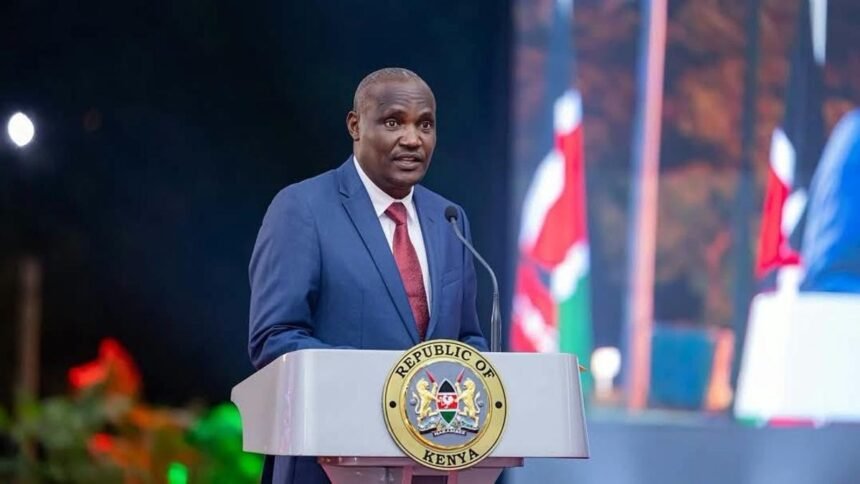
Kenya’s National Infrastructure Fund, the vehicle President William Ruto’s government created in March 2026 to mobilise up to Sh5 trillion for roads, rail, power and irrigation without adding to public debt, is facing that question eight days after naming its first CEO.
James Mworia, formerly chief executive of Centum Investment Company, was announced as founding CEO on September 7, 2026. On September 15, the High Court nullified the Sh204.3 billion sale of a 15% Safaricom stake to Vodacom, the transaction that made up nearly two-thirds of the fund’s seed capital.
Here’s what’s confirmed so far:
- The National Infrastructure Fund began with Sh310.3 billion in seed capital.
- That total is built from two privatisations: Sh106.3 billion from the Kenya Pipeline Company IPO, which closed in February 2026, and Sh204 billion from the Safaricom sale.
- The High Court ruled on September 15 that the Safaricom sale violated public finance law and fell short of the constitutional threshold for public participation, ordering the shares restored to the state.
- The government and Vodacom have both said they will appeal, and Vodacom has said it will seek a stay pending the outcome.
Kenya’s National Treasury confirmed at a formal handover in April 2026 that it had deposited all proceeds from the Kenya Pipeline offer into the fund. Before the Safaricom sale closed, Kenya Pipeline was the fund’s only privatisation-derived capital. That means the Safaricom transaction alone roughly tripled the fund’s base within its first four months of existence.
Kenya’s court found the Sh204.3 billion in Safaricom proceeds had not been tied to specific projects. The transaction had priced shares at Sh34 apiece and separately generated a further Sh40.2 billion through an advance on future dividends tied to the government’s remaining 20% Safaricom stake, bringing total Treasury receipts from the deal to Sh244.5 billion.
The seed-capital figure itself is not settled across public sources:
- Sh310.3 billion: reported by outlets, citing Mworia directly, as Sh106.3 billion (Kenya Pipeline) plus Sh204 billion (Safaricom).
- Sh340 billion: cited by a parliamentary committee report on the fund’s investment policy.
- Sh345 billion to Sh347 billion: cited in separate reporting, without a clear reconciliation against the other two figures.
Kenya’s Sh40.2 billion dividend advance falls outside the Sh310.3 billion figure Mworia cited, since Sh106.3 billion and Sh204 billion already account for the full total. Where that Sh40.2 billion was allocated instead, whether to a separate Sovereign Wealth Fund or elsewhere, has not been confirmed in public disclosures.
Kenya’s National Infrastructure Fund Act sets firm boundaries on how the fund can operate:
- The fund must publish audited financial statements, including a balance sheet, within three months of each financial year’s end. No such statement has yet been published.
- The fund is barred from borrowing against its own balance sheet, meaning it cannot leverage its way around a shortfall in seed capital if the ruling stands.
- No single project can account for more than 20% of the fund’s assets, and no single sector can exceed 40% exposure.
- Investments must target a minimum 7% equity return.
Kenya’s fiscal position explains why the Safaricom sale happened at all:
- Public debt has run above the 55% of GDP threshold recommended by the IMF and World Bank.
- Debt servicing has absorbed a large share of tax revenue in recent years.
- A 2024 attempt to close the gap through new taxation triggered nationwide protests and forced President Ruto to withdraw the Finance Bill.
- Treasury turned to asset monetisation instead, of which the Safaricom sale was the largest single transaction.
Here’s what happens next:
- The Court of Appeal will rule on Vodacom’s stay application, determining whether the fund’s capital base remains frozen near its pre-Safaricom level or reverts to Sh310.3 billion while the substantive appeal proceeds.
- Mworia has proposed listing a National Infrastructure Fund vehicle on the Nairobi Securities Exchange to draw in pension funds and asset managers, a plan that now depends on a capital base whose largest component is under court order to be unwound.
- The fund’s first audited financial statement, due under the Act, would be the first independently verifiable figure on what the fund actually holds.