The Making of the Kinshasa Stock Exchange
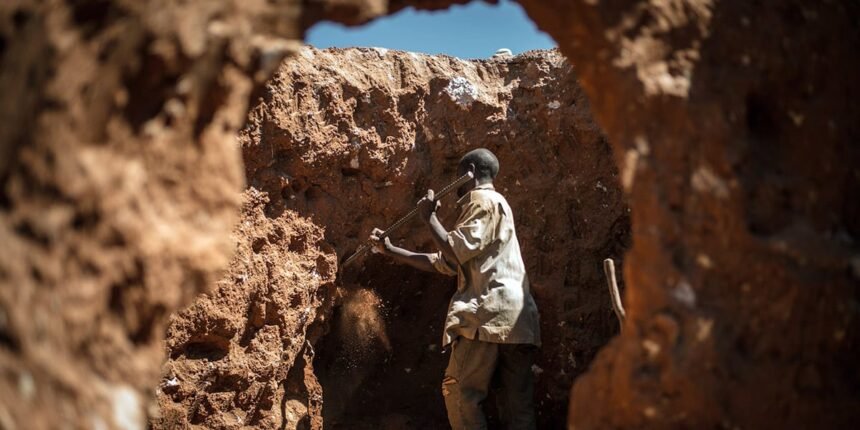
Financial markets have a habit of assigning countries a single identity and refusing to update it for years at a time.For the Democratic Republic of Congo, that identity has long been mineral abundance paired with institutional absence, a place where seventy per cent of the world’s cobalt sits beneath a state too thin to administer it. Investors who bought the country’s debut Eurobond in April did not so much reject that identity as demand a second one alongside it. They are now holding, simultaneously, a resource bet and a sovereign credit bet, and the DRC’s task for the rest of this decade is to keep those two bets from pulling in opposite directions.
The mechanics of the April issuance are by now familiar to anyone tracking frontier debt.
A $1.25 billion raise drew more than $5 billion in orders, split into a five-year tranche priced at 8.75 percent and a ten-year tranche at 9.5 per cent, arranged by Citigroup, Rawbank, and Standard Chartered and listed in London.
What deserves more attention than the oversubscription figure is the balance sheet that the DRC brought to the table. Debt to GDP of roughly 18 percent is a number Ghana, Kenya, and Ethiopia would each have envied at their own debut moments, when their ratios stood closer to 46, 42, and above 50 percent, respectively. Growth of 5.8 percent and inflation at 2.3 percent complete a picture that, on paper, looks less like a fragile frontier issuer and more like a conservatively run middle-income economy that happens to sit on some of the planet's most contested minerals.
That gap between balance sheet and reputation is precisely what the bond was priced to close. Yield spreads on Congolese paper are best read not as a verdict on solvency but as a premium for two things markets cannot yet observe directly: the durability of the ceasefire in the east and the state’s capacity to execute.
This is a subtle but important distinction. A country priced for fiscal fragility needs austerity to recover its standing. A country priced for execution risk needs institutions, and institutions take longer to build than budgets take to balance.
The Kinshasa Stock Exchange is the institution investors are being asked to wait for. Legislation permitting a securities exchange, a commodities exchange, a central securities depository, and settlement banks was adopted by the Cabinet in April 2025 and passed by the National Assembly in June of this year, with the Finance Minister defending it before the Senate on 11 June.
The regulator meant to police all of it, the Financial Markets Authority, exists at the same stage of development as the exchange. The International Finance Corporation’s cooperation agreement, signed in June, is explicitly aimed at closing that gap, covering regulatory design, market infrastructure, technical capacity, and eventual support through initial operations.
None of this is unusual by the standards of frontier market construction. What is unusual is the order of operations. Most emerging exchanges build a domestic constituency of listable companies first and seek international capital market credibility later. The DRC has run the sequence in reverse, establishing a sovereign benchmark before it has a functioning venue to price anything else against. The dividend from that reversal showed up almost immediately. A dollar-denominated domestic Treasury bond in May, targeting $70 million, drew bids of $86.6 million, and the government used the improved sentiment to extend maturity from eighteen months to two years while cutting the coupon from 9 to 8 percent.
The Eurobond, in other words, is already doing useful work on the DRC's cost of capital before the exchange it is meant to seed has opened.
Who gets to list, and what that says about the market’s shape
Reversing the sequence has consequences for what the eventual market will look like. Congolese law already requires banks, insurers and telecoms operators to organise as public limited companies, meaning those three sectors arrive structurally ready for listing while much of the rest of the economy, still substantially informal, does not.
Layered on top are national preference rules that will shape ownership from the first day of trading. Telecoms companies must reserve 25 percent of share capital for Congolese nationals and a further 5 percent for Congolese employees. Mining companies must allocate at least 10 percent to Congolese nationals, rising to 25 percent for small scale operators, with the state itself claiming a non-dilutable 10 percent stake at the point a permit is granted. Banks face a new ownership cap from July, limiting any single shareholder to 55 percent of capital.
The effect of these rules is to guarantee that the first generation of listed Congolese companies will be more state-adjacent and more nationally owned than a purely market-driven listing process would produce. That is not necessarily a flaw. It does mean that international investors buying into the Kinshasa exchange in its early years will be buying governance-constrained equity rather than the free-floating shares typical of a mature market, a structural feature worth pricing separately from ordinary country risk.
Historical comparison offers the DRC both comfort and warning in roughly equal measure. The comfort is the low leverage. The warning is what happened to countries that had it and squandered it. Zambia’s 2012 debut and Ghana’s 2007 issuance both arrived amid similar enthusiasm and similarly clean balance sheets, and both were followed within a decade by debt distress once early market access substituted for fiscal discipline rather than reinforcing it.
Congo Investment Group has made the point bluntly, arguing that capital access without institutional preparation produces volatility rather than systems, and that having proven it can raise money abroad, the DRC's real test is what it builds with the proceeds.
The minerals underneath all of this add a further layer of pricing complexity that has little to do with Kinshasa at all. The designation of lithium, cobalt, tantalum, niobium, tungsten and rare earths as strategic minerals earlier this year and the infrastructure competition between the American-backed Lobito Corridor and the Chinese-backed TAZARA railway for control of export routes mean the DRC’s medium-term fiscal position is partly a function of decisions made in Washington and Beijing rather than in Kinshasa alone.
A country whose export base is this geopolitically contested region rarely gets to fully control its own credit story, however well it manages its own institutions.
Put together, the honest position is that the DRC has passed the test investors control and has not yet passed the one it controls. Global capital has shown, decisively, that it will fund a well-managed balance sheet even in a country with a contested east and an underdeveloped bureaucracy.
The unresolved question is whether the Financial Markets Authority becomes a functioning regulator on a timeline measured in months rather than years, whether the informal sector produces enough transparent, bankable companies to give an exchange something to trade, and whether the government treats its low leverage as a foundation to build on rather than a credit line to spend.
Markets have priced the DRC as a frontier credit story with room to compress rather than a distressed one. Whether that pricing holds will be decided less by cobalt prices than by whether an institution most investors have never heard of manages to open its doors.