Africa’s largest industrial investment is now also its most ambitious test of financial integration.
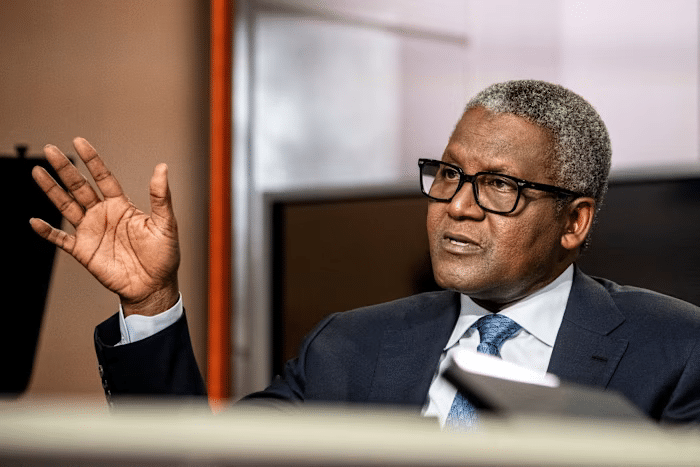
Months after Aliko Dangote first signalled his intention to list the refinery, the offering has moved from announcement to execution, presenting African markets with an opportunity to demonstrate that they can mobilise capital of this scale on their own terms.
The fifty billion dollar valuation target and the prospect of dollar dividends have drawn most of the attention. Equally significant is the coordinated effort, now underway across several exchanges, to allow a single listing to trade seamlessly across borders for the first time.
Dangote confirmed in May that the offering is targeting a September 2026 launch, telling journalists during a tour of the Lekki refinery that the group is working to have the IPO in the market by then. NGX’s chairman has since echoed that September timeline in remarks to investors. Earlier guidance, drawn from the original prospectus roadmap, had pointed to a June or July listing on the NGX main board, and the offering has already slipped once before, from an initial 2025 target to the current 2026 schedule. What is not in question is the underlying ambition: a listing intended to trade simultaneously across multiple African exchanges, an undertaking with no precedent on the continent.
The underlying asset accounts for much of the interest. Built with twenty billion dollars of private capital and no state funding, the refinery processes six hundred and fifty thousand barrels of crude a day, the highest throughput of any single-train refinery in the world. It produces Euro V grade diesel, tested at 87.6 parts per million sulphur, a substantial improvement on imported fuel that has tested as high as 2,000 ppm on Nigerian roads. The refinery exports forty percent of its output and has set a target of nearly doubling capacity to 1.3 million barrels a day by 2029. Against this sits 3.65 billion dollars in existing debt, a figure investors will need to weigh against the refinery's earnings capacity.
The offering’s currency structure represents its most significant innovation. Shares are subscribed for in naira through the Nigerian Exchange, but investors may elect to receive dividends in dollars, drawn from the refinery’s 6.4 billion dollars in annual export revenue. Nigeria’s Securities and Exchange Commission and the NGX granted special approval for the arrangement, reflecting a willingness among regulators to adapt existing rules to an asset of this scale. The structure allows investors exposure to a Nigerian asset without naira-denominated income risk, a feature that has extended the offering’s appeal well beyond Nigeria’s borders.
The cross-border infrastructure being assembled around the listing may prove as consequential as the listing itself. NGX is the primary listing, with secondary listings planned on the Nairobi Securities Exchange, the Ghana Stock Exchange, and the Johannesburg Stock Exchange, alongside the BRVM, which would extend access across eight West African markets.
Ethiopia’s new securities exchange is reportedly under consideration as a sixth venue. In April, the chief executives of these exchanges met in Lagos under the African Securities Exchanges Association to align listing frameworks across jurisdictions, pool retail investor demand across borders, build settlement infrastructure for shares trading on foreign registers, and address the regulatory friction that has historically kept African exchanges siloed from one another. NGX’s chairman framed the effort directly, stating that the continent’s economic future depends on how effectively its markets connect and how well it mobilises its own capital, rather than continuing to rely on external financing for infrastructure of this magnitude.
That coordination among exchanges is, in many respects, as significant as the transaction it supports. For the first time, the leadership of Africa's major bourses are treating a single listing as a test case for a genuinely continental capital market, one in which liquidity is pooled rather than fragmented across national borders. Should the cross-listing proceed as planned, it would establish a template that other African issuers could subsequently follow.
The economic case for the refinery, apart from the listing itself, is substantial. The African Development Bank estimates it could add 0.8 percentage points to Nigeria’s GDP annually over five years. Industry estimates put job creation across operations and supply chains above 135,000.
By displacing imported fuel, the refinery reduces the dollar outflow that has historically pressured the naira, and truckers are already reported to be paying fifteen percent less for diesel as a result of local supply. Its scale gives Nigeria the potential to become a regional fuel hub, undercutting the cost and lead time of importing refined products from Europe for neighbouring markets.
The business is also expected to support a planned quadrupling of fertiliser output at the Dangote Fertiliser plant and to supply raw material for plastics manufacturing, with downstream implications for food and manufacturing costs across the region.
These projections do not eliminate risk from the price, and a sound assessment of the opportunity must account for it. The valuation gap is the most immediate concern: Dangote is targeting forty to fifty billion dollars, while some analysts, working from construction costs, have placed fair value closer to twenty to twenty-five billion dollars, roughly half the upper end of management’s range. Naira volatility remains a risk for the local leg of the offering, notwithstanding the dollar dividend option. Crude supply disruptions, whether from pipeline security incidents or shipping constraints, sit alongside the refinery’s exposure to Brent and Dubai crude pricing as variables outside management’s control.
Nigerian investors can access the offering through licensed NGX brokers such as Stanbic IBTC, Meristem, CardinalStone or CSL, in conjunction with a CSCS clearing account. Investors in Kenya, Ghana and South Africa will be able to subscribe through local brokers once secondary listings are confirmed, in shillings, cedis or rand, while still receiving dividends in dollars.
Diaspora and international investors face a choice between the conventional route, involving a Non-Resident BVN and a Certificate of Capital Importation, and newer digital platforms built specifically around the offering, some of which waive the BVN requirement for foreign nationals and accept funding in dollars or stablecoins.
The Dangote listing offers a working demonstration of African capital, channelled through African exchanges, financing African infrastructure at global scale. The refinery itself, at 650,000 barrels a day and a fifty billion dollar valuation target, has already proven the industrial case. Whether the financial infrastructure being built around it can match that achievement remains the question now being tested.