The growing appetite for African corporate debt signals renewed confidence in businesses across the continent, with companies tapping international markets to raise financing for their operations and investment plans.
Between January and September, the $13.3 billion raised included $3.25 billion in private placements, according to Bank of America. The total is the second-highest on record after the $17 billion raised in 2021.
Bank of America expects African corporate bond issuance to remain between $8 billion and $12 billion annually over the coming years, supported by stronger credit profiles and increased access to international financing.
Kay Hope, the bank’s managing director for global research, said the market was benefiting from improving credit fundamentals.
“Credit quality is improving, upgrades outnumber downgrades, and returns by rating tend to beat EM averages,” Hope said in a research note, referring to emerging markets.
More African countries access international capital
The recovery is also spreading across more markets. Companies from 11 African countries issued bonds in 2026, compared with eight in 2021, highlighting a broader range of businesses seeking funding from international investors.
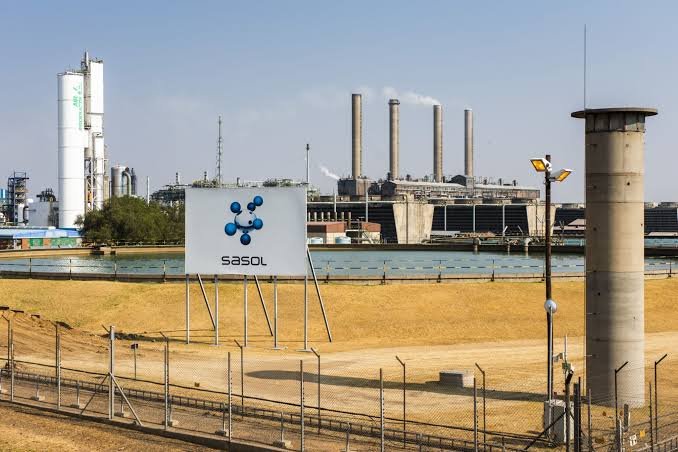
Among the companies that have accessed the market this year are Zambia-linked mining group First Quantum Minerals, Angola’s Azule Energy and South Africa’s petrochemicals producer Sasol.
The participation of businesses across mining, energy and industrial sectors underscores the role of international debt markets in financing companies operating in capital-intensive industries.
Investors are increasingly drawn to the returns offered by African corporate bonds relative to other emerging-market debt. Bank of America said returns across credit-rating categories had exceeded emerging-market averages, while rating upgrades had become more common than downgrades.
The volume of corporate debt rated CCC, one of the lowest credit-rating categories, has also declined to $2.1 billion from $3.2 billion five years ago. The reduction suggests that the riskiest segment of the market has become smaller, although significant credit risks remain.
High borrowing costs could slow momentum
Despite the stronger issuance figures, the outlook is not without challenges. Higher interest rates could make borrowing in foreign currencies expensive for companies looking to refinance existing debt.
Some businesses may therefore turn to domestic bond markets, commercial bank loans or investors in Gulf countries rather than issue international bonds.
However, if credit spreads — the additional return investors demand for taking on credit risk — continue to narrow, financially stronger companies and established borrowers could find it easier to raise funds internationally.
For African businesses, the ability to access financing on favourable terms will remain important for managing cash flow, funding expansion and refinancing existing obligations.
Debt repayments set to rise in 2028
One of the biggest challenges facing African corporate borrowers is the growing volume of debt coming due over the next two years.
United Bank for Africa has a $300 million bond maturity due in November 2026. Repayment obligations are expected to increase to $2.2 billion across four issuers in 2027 before climbing to nearly $7 billion across nine issuers in 2028.
The largest repayments scheduled for 2028 include $1.5 billion for South African power utility Eskom, $1.2 billion for oil producer Tullow Oil and $1 billion for logistics company Transnet.
The concentration of maturities could put pressure on companies to secure refinancing well ahead of their repayment dates. Businesses could face higher costs if global interest rates remain elevated or investors become more cautious about emerging-market debt.
The ability to refinance these obligations without putting pressure on operations and cash flow will be a critical test for African companies over the coming years.
Sovereign debt remains a key risk
While corporate credit conditions are improving, financial difficulties facing African governments could undermine the progress made by businesses.
Bank of America estimates that approximately 7% of the $149 billion in sovereign debt covered by its analysis carries CCC or CC ratings, indicating substantial credit risk. Senegal’s ongoing pursuit of debt restructuring highlights the continued pressure on public finances in parts of the continent.
“Sovereign stress is a key risk to bear in mind,” Hope said.
Government debt distress can push up borrowing costs for companies, weaken investor confidence and limit the credit ratings available to businesses operating in affected countries. Even companies with relatively strong balance sheets may face constraints because their ratings can be capped by the creditworthiness of their home governments.
The $13.3 billion raised in the first nine months of 2026 points to renewed investor interest in African businesses.