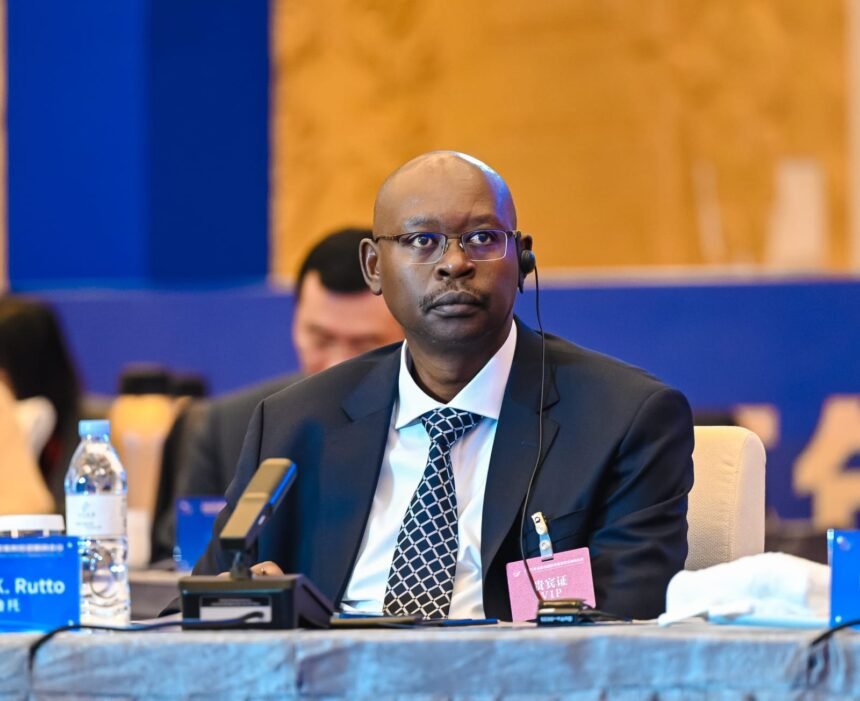
By Dr. Erick Rutto, President, Kenya National Chamber of Commerce and Industry
Africa’s economy is now approaching $3.7 trillion. We have signed the largest free trade agreement in the world by number of countries, bringing 54 nations into a single market. On paper, the African Continental Free Trade Area is a triumph of political will.
In practice, we still trade more with the rest of the world than we do with each other.
Intra-African trade sits at between 15 and 18 percent of our total trade, worth around $300 billion out of roughly $1.5 trillion in trade flowing in and out of the continent. Compare that with our peers: intra-regional trade among Asian economies runs at around 60 percent. The European Union manages closer to 67 percent.
The trade bloc linking the United States, Mexico and Canada is higher still. Africa has a $1.2 trillion opportunity sitting on the table, and we are not yet reaching for it. The AfCFTA Secretariat’s own target is to double our intra-African trade share by 2035. That is an ambitious goal, and it is achievable, but only if businesses, not just governments, do the work of making it real.
I do not say this to dwell on the shortfall. I say it because the gap is the opportunity, and because the businesses that close it will be the ones that build Africa’s next generation of industry, jobs and wealth.
What is actually standing in the way
Agreements do not move goods across borders. Businesses do, and they can only do it as fast as the systems around them allow.
Infrastructure is one constraint. Kenya’s LAPSSET corridor, designed to move goods from the Indian Ocean to the Atlantic in a single day, is the kind of investment that changes what is possible, but it takes years to build. We cannot wait for every road and railway to be finished before we start trading more with each other.
Trade finance is a sharper and more immediate problem. Globally, the large majority of trade is financed. In Africa, our own research puts the figure for intra-African trade closer to 20 percent, because banks perceive cross-border trade on the continent as too risky. That perception gap, not a shortage of goods to sell, is what keeps many of our small and medium enterprises confined to their home markets. When settlement has to route through institutions outside the continent, businesses absorb transaction costs of 10 to 15 percent above the global norm. That single margin can be the difference between a competitive product and one priced out of the market.
Then there is information.
In our own surveys, Kenyan businesses rank a lack of market information as the third-biggest obstacle to trading across the continent. Businesses cannot sell into markets they do not understand, to buyers they have never met, under rules they have never seen written down.
What is already changing
None of this is static, and some of it is moving faster than most people realise.
The Guided Trade Initiative, which started with eight countries including Kenya, Ghana, Egypt and Algeria, had grown to 37 of the 54 AfCFTA signatories by the end of 2025, working through tariff barriers, rules of origin and customs procedures one bottleneck at a time. The Pan-African Payment and Settlement System now links a growing share of the continent’s countries and banks, cutting out the detour through correspondent banks abroad. The African Guarantee Fund has backed Kenyan banks with guarantees to help small and medium enterprises access trade finance, on top of the billions the African Development Bank has committed continent-wide.
At the Kenya National Chamber of Commerce and Industry, we have taken the same approach at ground level. We operate through 47 chapters, one in every county, so that a business in Kitale has the same access to trade facilitation and rules-of-origin training as one in Nairobi. Through our ISO digital marketplace, we have helped digitise more than 80,000 companies across Kenya, Uganda, Tanzania, Burundi and Rwanda, giving small businesses a trust-verified presence online.
We have led trade missions to Zambia, Ethiopia and Zimbabwe, and helped Kenyan companies gain listings in Zambian retail chains. With the European Union and the Lithuanian Chamber, we trained 478 women-led businesses to export into the EU market. And because the overwhelming majority of Kenya’s roughly 7.4 million businesses are small or medium enterprises, we run dedicated women-in-business and youth-in-business structures in every one of our 47 chapters, with board-level representation to make sure their concerns reach where decisions get made.
We are also pushing, as our top policy priority, for a single trusted certifying body across the 54 AfCFTA member states, so that a certificate of origin or a standards clearance issued in Nairobi is accepted at face value in Johannesburg, Accra or Casablanca, without a second inspection at every border.
What success looks like
We have set ourselves a clear target: help close a meaningful share of that $1.2 trillion opportunity, not through speeches, but through signed investment deals, joint ventures, and financial institutions putting real capital behind African small and medium enterprises trading across borders.
That is the purpose of the Africa Commerce and Industry Summit, which the Kenya National Chamber of Commerce and Industry will convene in Nairobi from 14 to 16 October, as part of our 60th anniversary. We expect more than 5,000 delegates and 350 exhibitors, alongside investors, government leaders and business chambers from across the continent. It is built for business-to-business and business-to-government matchmaking, because that is what turns a trade agreement into an actual shipment.
My invitation is simple, and it applies whether you run a multinational or a maize farm in Kitale with an eye on an export market. Show up. Bring your product. Find your new business partner.
The single market we have signed into existence will only become real one transaction, one relationship and one deal at a time. Let us use this October to place a few more of them on the table.