What to know
- Africa ran a deficit of almost US$8.0 billion in textiles and US$3.3 billion in clothing in 2020, according to the Southern African Customs Union.
- Francophone Africa produced 1.062 million tonnes of cotton lint in 2020/21 and processed about 11,000 tonnes of it in its own mills.
- A June 2024 International Trade Centre study found that processing 25% of the C4+ countries’ cotton locally would need about US$5 billion and could create 500,000 jobs.
- The Partenariat pour le Coton launched Africa Textile Invest, a platform for investors, in Yaoundé in March 2026.
- Processing half of Africa’s cotton domestically by 2030 has been estimated to require about US$25 billion across spinning, weaving, knitting and garmenting.
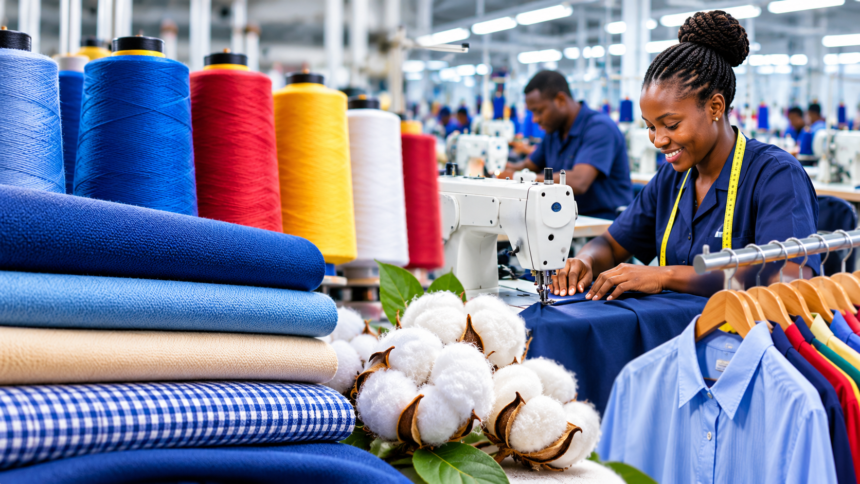
Africa has the cotton, the labour, preferential access to major consumer markets and a rising share of the world’s certified sustainable fibre. Its textile and apparel industry is thin in the stages between the farm and the finished garment: spinning, weaving, knitting, finishing and garment assembly. Those stages decide how much of the value in each bale stays on the continent.
The trade figures show the cost. Africa’s clothing imports rose from just over US$9.9 billion in 2016 to US$13.6 billion in 2020, and textile imports climbed from US$7.6 billion to US$9.4 billion over the same period, according to the Southern African Customs Union. Textile imports were worth more than seven times textile exports. The continent closed 2020 with a deficit of almost US$8.0 billion in textiles and US$3.3 billion in clothing.
Governments and lenders have begun to put money and platforms behind the shift. The Partenariat pour le Coton, backed by the World Trade Organization, the UN Industrial Development Organization and the International Trade Centre, turned its focus to mobilising investment at a high-level event in Yaoundé on 25 March 2026, on the eve of the WTO’s 14th Ministerial Conference. Partners launched Africa Textile Invest, a single access point for investors to country data, industrial zones and a pipeline of projects, the WTO said. Afreximbank says it has committed US$2 billion to cotton sector transformation in Nigeria, and that its cotton industrialisation programme aims to create 500,000 jobs and US$10 billion in import substitution by 2030.
Abundant cotton, limited processing
West Africa, and the Francophone cotton economies in particular, produces about two-thirds of Africa’s cotton. Most of that fibre leaves the region with little processing. Francophone Africa produced 1.062 million tonnes of cotton lint in 2020/21 and consumed about 11,000 tonnes industrially, roughly 1% of its output. Southern Africa produced 482,000 tonnes and consumed 197,000 tonnes, about 41%. North Africa produced 199,000 tonnes and consumed 142,000 tonnes, about 71%. The continent’s largest cotton producers are its smallest processors.
Installed machinery follows the same pattern. Africa had roughly 4.0 million to 4.2 million ring spindles in 2020, compared with about 201 million across Asia and Oceania, a ratio of about one to fifty. Africa held around 20,000 shuttle-less looms against 1.478 million in Asia and Oceania, a ratio of about one to seventy-four. Spinning and weaving capacity determines where the manufacturing margin above raw fibre is earned.
Why the timing favours Africa
Brands and retailers have been spreading their sourcing beyond concentrated Asian supply chains to manage risk and shorten delivery times. Africa enters those decisions with a sustainability record buyers can verify. Sub-Saharan Africa’s share of global preferred cotton supply rose from 9% in 2014/15 to 30% in 2019/20.
Labour costs are competitive. Monthly wages in Ethiopia, Madagascar and Burkina Faso have been cited at US$75 to US$100, compared with US$600 in China and US$275 in Vietnam.
Preferential market access is in place and has been extended. US lawmakers approved a two-year extension of the African Growth and Opportunity Act in September 2026, keeping duty-free access for eligible countries through 31 December 2028. The programme had lapsed on 30 September 2025 and was restored for one year in February 2026. European Union trade arrangements and the African Continental Free Trade Area (AfCFTA) offer further routes to scale regional and export manufacturing.
The investment case now carries numbers. The International Trade Centre’s June 2024 study found that the C4+ countries, Benin, Burkina Faso, Chad, Mali and Côte d’Ivoire, could process up to 25% of their cotton within ten years. That would require about US$5 billion in production facilities and workforce training and could create 500,000 jobs, especially for women and young people, according to the study.
Wages are one input among several
African apparel manufacturing can win on wages, and factories are priced on far more than wages. Productivity, technical skills and supervisory capacity decide how much output each low-cost hour delivers. Electricity tariffs are very low in some markets, Ethiopia among them, and reach up to US$0.15 per kilowatt-hour in Kenya and Burkina Faso.
Market access depends on meeting rules of origin and on firms having the capacity to use the preferences available to them. The cotton base is strong, while local spinning, weaving and finishing remain limited. Development finance institutions have shown growing interest in the sector, and commercial borrowing costs stay high and trade finance scarce.
Investors therefore assess African textile locations as integrated industrial systems, weighing power, water, logistics, skills and finance alongside the wage bill.
Benin’s cotton reforms
Benin shows what coordinated reform of a cotton sector can deliver. Seed cotton output rose from 597,373 tonnes in 2017/18 to 678,000 tonnes in 2018/19, making Benin Africa’s leading producer, according to government figures. Production reached 714,714 tonnes in 2019/20 and 728,000 tonnes in 2020/21, and Benin has held the top position since.
The gains reached the wider economy. Benin’s GDP grew 6.9% in 2019, up from 6.7% in 2018, with cotton output and ginning among the main contributors to primary sector growth, according to UMOA-Titres, the West African regional securities agency.
Benin is now moving downstream. Raw cotton that generated about US$40 million in export receipts can yield up to US$800 million once processed into garments at the Glo-Djigbè Industrial Zone, according to Afreximbank.
Where the value is created
The journey from cotton to clothing passes through six stages. Cotton farming and ginning are Africa’s current strength. Spinning converts lint into yarn, and weaving and knitting turn yarn into fabric. Dyeing, printing and finishing add product differentiation and the testing and certification buyers require. Cut, make and trim covers garment assembly. Design, branding and retail sit at the highest-value end.
Africa is strong at the first stage and present in parts of the last two. The largest opportunity lies in spinning, weaving, knitting and finishing.
Five priorities in the plans on the table
The plans now being financed share five priorities. The first is infrastructure: reliable power, water, logistics, industrial parks and export facilities built as ecosystems around clusters of factories. The WTO, UNIDO and their partners named access to energy, skills and infrastructure among the core goals when they agreed the West African cotton initiative in July 2024.
The second is converting market access into market share, using AGOA, EU preferences and the AfCFTA to build regional supply chains as well as export assembly. The third is a secure supply of quality cotton, supported by smallholder programmes, certified seed systems, sound agronomic practice and traceable sustainable fibre.
The fourth is anchor investment from vertically integrated manufacturers and brand vendors able to build local supplier networks around them. The fifth is people and institutions: technical training for machine operators, supervisors and quality-control specialists, and strong industry associations.
The US$25 billion question
Transforming 50% of Africa’s cotton domestically by 2030 has been estimated to require about US$25 billion in investment across spinning, weaving, knitting and garmenting. The figure covers factories and the assets that make them viable: power, water treatment, freight corridors, testing laboratories, workforce training and trade finance.
The C4+ estimate offers a regional benchmark. Processing a quarter of those five countries’ cotton would take about US$5 billion over a decade and support roughly 500,000 jobs, according to the International Trade Centre. WTO Deputy Director-General Jean-Marie Paugam said in May 2025 that mobilising that capital would require the C4+ countries to lead and to take a regional approach to attracting and keeping investment.
What to watch
- Project announcements and financial close for opportunities listed on Africa Textile Invest under the Partenariat pour le Coton’s 2026 to 2030 investment framework.
- Afreximbank’s progress toward its 2030 targets of 500,000 jobs and US$10 billion in import substitution through cotton industrialisation.
- How exporters use the AGOA extension to 31 December 2028, and the conditions Washington attaches to continued eligibility.
- Garment output and exports from Benin’s Glo-Djigbè Industrial Zone as a measure of how fast processing capacity can scale.
- Implementation of AfCFTA rules of origin for textiles and clothing, which will shape how much regional yarn and fabric qualifies for preferential trade.