Kenya is moving towards developing a National Credit Score as the government and financial sector seek new ways to bring millions of underserved borrowers into the formal credit market.
Principal Secretary for MSME Development Suzanne Mang’eni said the proposed score will draw on behavioural data from the Hustler Fund, alongside alternative data sources, giving lenders a broader picture of borrowers beyond traditional credit histories and collateral.
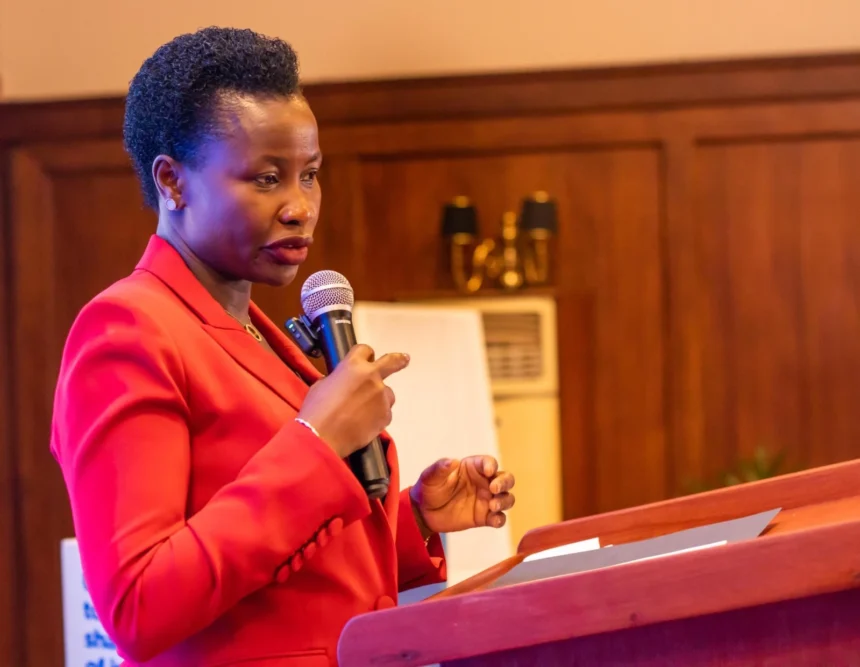
Speaking at the 3rd National Credit Market Convention in Naivasha organised by Metropol, PS Mang’eni said Kenya needs to rethink how it assesses risk, particularly when dealing with young people, women and small businesses that may have limited assets but have the capacity to repay.
“We need to shift our focus from the individual to the environment itself,” she said, arguing that socioeconomic conditions should also be considered when assessing a borrower’s risk.
The proposed score is being developed against a backdrop of a large financing gap facing Kenya’s MSME sector. PS Mang’eni put the gap at about Ksh.2.6 trillion ($20 billion), warning that the figure could be even higher as new businesses continue to emerge.
PS Mang’eni said the problem is not simply a shortage of businesses seeking money, rather, many micro and small enterprises struggle to move up the business ladder.
“The micro are not moving to small and the small are not moving to medium and the medium are not exiting to large enterprise,” she said. “This is the biggest problem that we need to work together and see how we work it out.”
From credit history to alternative data
The Kenyan government has been working with the World Bank and International Finance Corporation (IFC) on expanding the sources of alternative data that can be used to build credit profiles.
PS Mang’eni said the work is aimed at creating stronger digital profiles for borrowers who may not have enough conventional financial information to satisfy lenders.
“How do we start establishing the data trail?” she asked. “How can we leverage on what is happening to start creating digital profiles, new credit profiles? How do we expand the sources of data?”
The Central Bank of Kenya (CBK) has also been pushing for greater use of alternative data in credit scoring, particularly to widen access to finance for MSMEs. Its credit-reporting reforms include expanding credit information and improving the predictiveness of credit scores.
Under Kenya’s credit-information framework, Credit Reference Bureaus (CRBs) can also work with approved third-party credit information providers, allowing them to build more comprehensive borrower profiles.
Turning behaviour into a credit profile
The Hustler Fund is expected to play a major role in the new system. PS Mang’eni said the government and private-sector partners have been able to observe repayment behaviour through the platform, creating a pool of information that could eventually feed into the national score.
“We are building a national credit score,” she told over 250 delegates.
She said the system would use the experience of the Hustler Fund and data collected through private-sector infrastructure to develop a rating system that goes beyond simply determining whether someone can access a loan.
The State Department for MSME Development has separately said the National Credit Score is being developed using Hustler Fund behavioural data and alternative data, to expand formal credit-market participation and access to affordable credit.
What this means is that a borrower without land, a large bank balance or other traditional collateral could potentially build a stronger financial profile through actual financial behaviour.
“Your credit rating can now become your net worth. It can become your collateral.”
The challenge now is turning that ambition into a system that lenders can trust, borrowers understand and businesses can use.