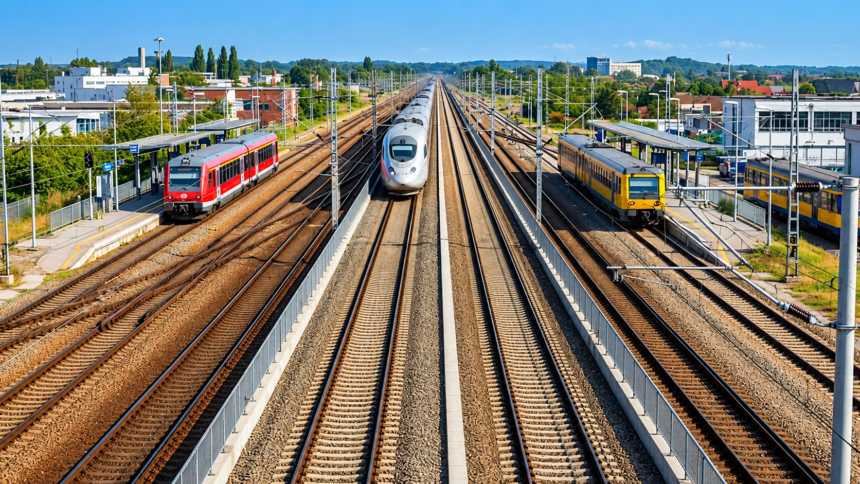
Morocco has unveiled a railway investment programme worth more than $11.2 billion through 2030, placing transport infrastructure at the centre of its economic development and efforts to strengthen regional connectivity.
The plan was announced in Rabat on Wednesday during the second International Forum on Investment and Financing Solutions for the Future of Railways in Africa, which brought together development banks, investors, financial institutions and railway officials to explore ways of financing major rail projects across the continent.
According to Mohamed Rabie Khlie, director general of Morocco’s National Railways Office (ONCF), the programme will extend the country’s high-speed rail network towards Marrakech, expand urban rail services and introduce 660 new railcars and trains.
The high-speed expansion is expected to create a 630-kilometre network, building on Morocco’s experience operating Al Boraq, Africa’s first high-speed train.
Morocco’s existing railway network carries more than 55 million passengers annually, highlighting the growing role of rail transport in moving people and supporting economic activity.
A bigger push for infrastructure investment
The railway expansion forms part of a 134 billion dirham ($13.6 billion) investment programme outlined by Morocco’s transport ministry. The plan includes extending high-speed rail services, connecting the Nador West Med port to the railway network, improving regional train services and acquiring 168 additional trains.
The programme is also linked to Morocco’s preparations to co-host the 2030 FIFA World Cup, when demand for efficient transport and logistics is expected to increase.
Beyond passenger transport, improved railway connections could strengthen freight movement between ports, industrial centres and major cities, helping businesses move goods more efficiently.
Why Africa needs new ways to finance railways
The discussions in Rabat touched on challenges facing many African countries: building railway infrastructure requires substantial upfront investment, while returns often take years to materialise.
Khlie warned that infrastructure deficits cost Africa around 2% of annual economic growth and can reduce productivity by as much as 40%.
He called for a shift from discussing infrastructure gaps to developing projects that can attract financing and move into implementation.
Public budgets alone are unlikely to meet the continent’s railway investment needs. Governments are therefore being encouraged to work more closely with development banks, private investors and other financial institutions.
The forum also highlighted the importance of ensuring that railway projects have sustainable funding for maintenance and operations, rather than focusing only on construction costs.
Could green finance unlock more funding?
Environmental benefits are emerging as another potential source of financing.
François Davenne, director general of the International Union of Railways, argued that rail transport’s contribution to reducing emissions should be better recognised by financing institutions.
He cited a study suggesting that railways could help avoid 1.8 gigatons of carbon emissions in developing countries by 2050, potentially generating between $27 billion and $72 billion in revenue through carbon markets.
However, he said carbon prices used in studies were significantly higher than prevailing market prices, and that there’s a need for stronger mechanisms to translate environmental benefits into actual funding.
What this means for Africa
For African economies, stronger railway networks could reduce transport costs, connect farmers and manufacturers to larger markets, create jobs and improve access to international trade routes.
But turning these ambitions into reality will depend on more than securing construction funding. Countries must also prepare commercially viable projects, manage financial risks, coordinate cross-border standards and ensure that railway services remain affordable and reliable.